
On this page
- 1How to pay for a kitchen remodel
- 2Know your number before you pick a loan
- 3Kitchen remodel financing options compared
- 4Paying with savings
- 5Using a HELOC for a kitchen remodel
- 6Home equity loan
- 7Cash-out refinance
- 8Should I use a HELOC or a cash-out refinance for a kitchen remodel?
- 9Personal loans and credit cards
- 10Can you get a loan for a kitchen remodel?
- 11Questions to ask a lender before you borrow
- 12How payment timing works with a contractor
- 13Ways to lower what you need to borrow
- 14Mixing savings and a loan
- 15How we help you plan the money side
- 16FAQs
- 17Choose how to pay before you sign
A kitchen remodel is one of the largest checks most homeowners write. Few people pay it all from one savings account.
How to pay for a kitchen remodel changes your real cost and your risk. Pick the method before you sign a contract.
How to pay for a kitchen remodel
Most homeowners pay with savings, a home equity line of credit (HELOC) or a home equity loan. Others use a cash-out refinance or a personal loan. Many combine two. The best way depends on your equity, your rate and how fast you can repay.
Cash costs nothing in interest. Home-secured loans often have lower rates but put your home at risk if you fall behind.
Know your number before you pick a loan
Start with the full project cost, including sales tax and an allowance. Then decide how much to borrow.
In Washington, sales tax applies to the full remodel contract price. In Bellevue, the combined rate is 10.3% for October through December 2026, per the Department of Revenue.
For scale, Cost vs Value 2025 puts a Pacific minor midrange kitchen at $29,728. A major midrange one runs $86,480. Your number depends on your scope.
Borrow for the real total. Running short mid-job is worse than borrowing a little extra.
Kitchen remodel financing options compared
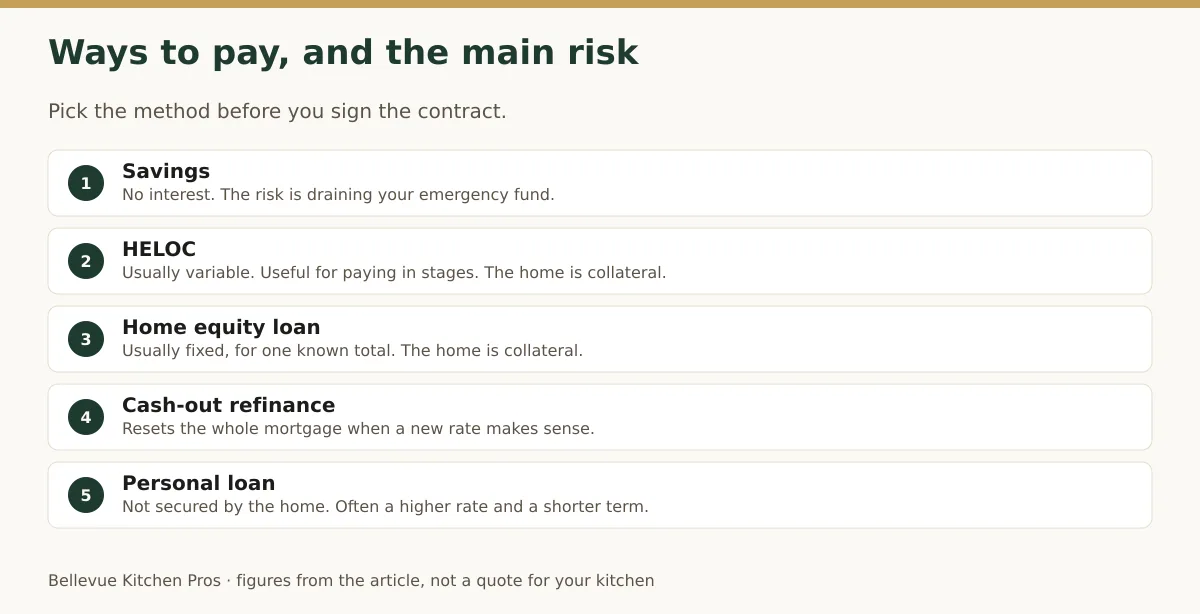
Each option trades cost, speed and risk differently. Home-secured options use your house as collateral. Unsecured options do not, but often cost more.
| Option | Secured by your home? | Rate type | Best for | Main risk |
|---|---|---|---|---|
| Savings | No | None | Anyone with the cash | Draining your emergency fund |
| HELOC | Yes | Usually variable | Paying in stages | Rising payments; home at risk |
| Home equity loan | Yes | Usually fixed | One known total | Home at risk if you fall behind |
| Cash-out refinance | Yes | Fixed or variable | When a new mortgage rate makes sense | Resets your whole mortgage |
| Personal loan | No | Usually fixed | Smaller projects, little equity | Higher rates, shorter terms |
| Credit card | No | Variable | Small items you can pay off fast | High interest |
Rates and terms change often. Compare offers from more than one lender before you choose.
Paying with savings
Savings is the cheapest way to pay because there is no interest. The trade-off is less cash on hand for emergencies.
Keep a cushion after the remodel. A kitchen job can turn up repairs behind the walls, so hold back money for that too.
Some people pay most of the project in cash and borrow a small amount for the rest. That keeps interest low while protecting savings.
Using a HELOC for a kitchen remodel
A HELOC is a line of credit against your home’s equity. You draw money as needed, which fits a remodel paid in stages.
The Consumer Financial Protection Bureau explains the key points:
- A HELOC lets you borrow against the equity in your home.
- HELOCs “usually have a variable interest rate,” so payments can change.
- You can draw during a set draw period, which “could last 10 years, for example.”
- Payments are often higher once the draw period ends.
The CFPB is direct about the risk: “If you fall behind or can’t repay the loan on schedule, you could lose your home.”
A HELOC fits kitchen projects well because you pay contractors in phases. You only pay interest on what you have drawn.
Home equity loan
A home equity loan gives you one lump sum against your equity, usually at a fixed rate. It fits a project with a known total.
You get predictable payments. That helps if you want a set budget and a set payoff date.
The downside is that you borrow the full amount up front. You pay interest on it even before the contractor needs it.
Like a HELOC, it is secured by your home.
Cash-out refinance
A cash-out refinance replaces your mortgage with a larger one and gives you the difference in cash.
It can make sense if a new mortgage rate is close to or below your current one. If your current rate is lower, you may end up paying more on your whole balance.
Closing costs also apply. Run the numbers on the full mortgage, not just the remodel portion.
Should I use a HELOC or a cash-out refinance for a kitchen remodel?
Use a HELOC if you like your current mortgage rate and want to draw in stages. Consider a cash-out refinance if a new rate would improve your mortgage overall.
| Question | HELOC | Cash-out refinance |
|---|---|---|
| Keeps your current mortgage? | Yes | No, it replaces it |
| How you get money | Draw as needed | One lump sum at closing |
| Rate type | Usually variable | Fixed or variable |
| Closing costs | Often lower | Usually higher |
| Fits a staged payment schedule? | Yes | Less well |
Talk to a lender or financial adviser about your own numbers. This is general information, not financial advice.
Personal loans and credit cards
Personal loans and credit cards do not use your home as collateral. They are faster to get but usually cost more.
A personal loan can fit a smaller project or a homeowner with little equity. Terms are often shorter, so payments can be higher.
Credit cards work for small items you can pay off quickly. High interest makes them a poor choice for a whole kitchen.
Can you get a loan for a kitchen remodel?
Yes. Banks, credit unions and online lenders all offer home equity and personal loans for remodels.
Lenders look at your credit, your income and, for home-secured loans, your equity. Having a written quote helps you ask for the right amount.
Some contractors offer financing through a partner. Compare it with outside offers, since the rate and fees can differ.
Questions to ask a lender before you borrow
Ask about the rate, the fees, the repayment terms and what happens if your home value drops. Get the answers in writing.
Useful questions:
- Is the rate fixed or variable? How high can it go?
- What are the closing costs and annual fees?
- How long is the draw period, and what do payments look like after it?
- Can you pay it off early without a penalty?
- Can the lender freeze or lower your line if home values fall?
The CFPB notes a lender may freeze new HELOC draws if your home value drops a lot. Plan for that risk if your project runs long.
How payment timing works with a contractor
Most kitchen remodels are paid in stages tied to finished work. That timing matters when you choose how to borrow.
Washington L&I advises: “Besides a reasonable down payment, you should pay your contractor only when specific phases of a project are completed.” It also says to avoid paying in full until all work is done.
A HELOC lines up well with staged payments. A lump-sum loan means some money sits idle until each stage.
For a safe schedule, see our guide on kitchen remodel deposits and payment schedules.
Ways to lower what you need to borrow
Shrinking the scope or timing your purchases can cut what you finance.
What works:
- Keep the layout. It avoids new plumbing, gas lines and many permits.
- Choose semi-custom cabinets over custom when sizes allow.
- Reuse good appliances if they fit the new plan.
- Check rebates. PSE offers $1,000 back on qualifying heat pump water heaters installed in 2026.
- Plan the full scope once. Change orders add cost you may need to borrow.
Common mistakes:
- Borrowing for the quote without tax or an allowance.
- Paying a large deposit from borrowed money before work starts.
- Picking a loan before comparing at least two lenders.
To see what a set budget buys, read our guide to a $50,000 kitchen remodel.
Mixing savings and a loan
Many homeowners pay part in cash and borrow the rest. That keeps interest low and protects savings.
One common approach is to pay the deposit and early phases from savings. Then draw from a HELOC for the later phases.
Keep an emergency cushion either way. Kitchen jobs can turn up repairs behind the walls.
Talk with a lender or financial adviser about your own numbers before you commit to any loan.
How we help you plan the money side
Bellevue Kitchen Pros plans and builds kitchens from start to finish. We do not lend money, but we help you plan the number you need.
You get an itemized quote with sales tax, permits and allowances shown. You also get a payment schedule tied to finished phases, which fits a HELOC or staged savings.
See how our pricing works on the kitchen remodel cost in Bellevue page.
FAQs
What is the best way to finance a kitchen remodel?
There is no single best way. Savings costs no interest. A HELOC fits staged payments and keeps your current mortgage. A home equity loan suits a fixed total with fixed payments. A personal loan avoids using your home as collateral. Compare offers and choose based on your equity, rate and repayment plan.
Is a HELOC a good idea for a kitchen remodel?
It can be. A HELOC lets you draw money as each phase finishes. You pay interest only on what you use. Rates are usually variable, so payments can rise. The CFPB warns that you could lose your home if you cannot repay. Borrow only what you can comfortably pay back.
How do people pay for a kitchen remodel?
Many homeowners use a mix of savings and home equity. Others use a home equity loan, a cash-out refinance or a personal loan. Payments to the contractor usually come in stages tied to finished work. Washington L&I advises paying only a reasonable down payment, then paying as phases are completed.
Can I finance a kitchen remodel with no equity?
Yes, but your options are narrower. A personal loan does not use your home as collateral. Some contractors offer financing through a lending partner. Rates are often higher than home equity options. Keep the scope tight, and compare the total interest cost before you sign.
Should I include sales tax in my loan amount?
Yes. Washington sales tax applies to the full contract price of a remodel. In Bellevue, the combined rate is 10.3% for October through December 2026. Leaving it out can leave you short when the final invoices arrive. Add an allowance for repairs found behind the walls too.
Choose how to pay before you sign
The best way to pay for a kitchen remodel balances cost, risk and timing. Know your full number, compare lenders and match the loan to a staged payment plan.
Book a consultation for an itemized quote and payment schedule to take to your lender.
Written by
Daniel Brooks
Daniel Brooks has worked in kitchen remodeling since 2020. He leads the planning guides at Bellevue Kitchen Pros and focuses on Bellevue kitchen remodels: how layouts, cabinets and counters fit local homes, what the City of Bellevue requires for permits, and how costs break down from a minor refresh to a full remodel. He writes in plain steps, links every figure to its source, and updates guides when local rules or prices change.
Planning notes are general. Confirm engineering, permits, and price with a licensed Washington contractor.